Richard Thaler’s observation, “If we use prediction as the measure of a model, traditional finance makes precisely wrong predictions,” cuts to the core of rational investor theory’s fallacy. Nowhere is this more apparent than in the Indian retail investment landscape, where deep-seated psychological biases, often masked by cultural nuances, drive suboptimal financial decisions. Today, we dissect one such insidious bias: Mental Accounting. This isn’t about market fluctuations or IPO performance; it’s about the invisible mental ledger distorting your perception of wealth and risk.
The Architect of Illogic: What is Mental Accounting?
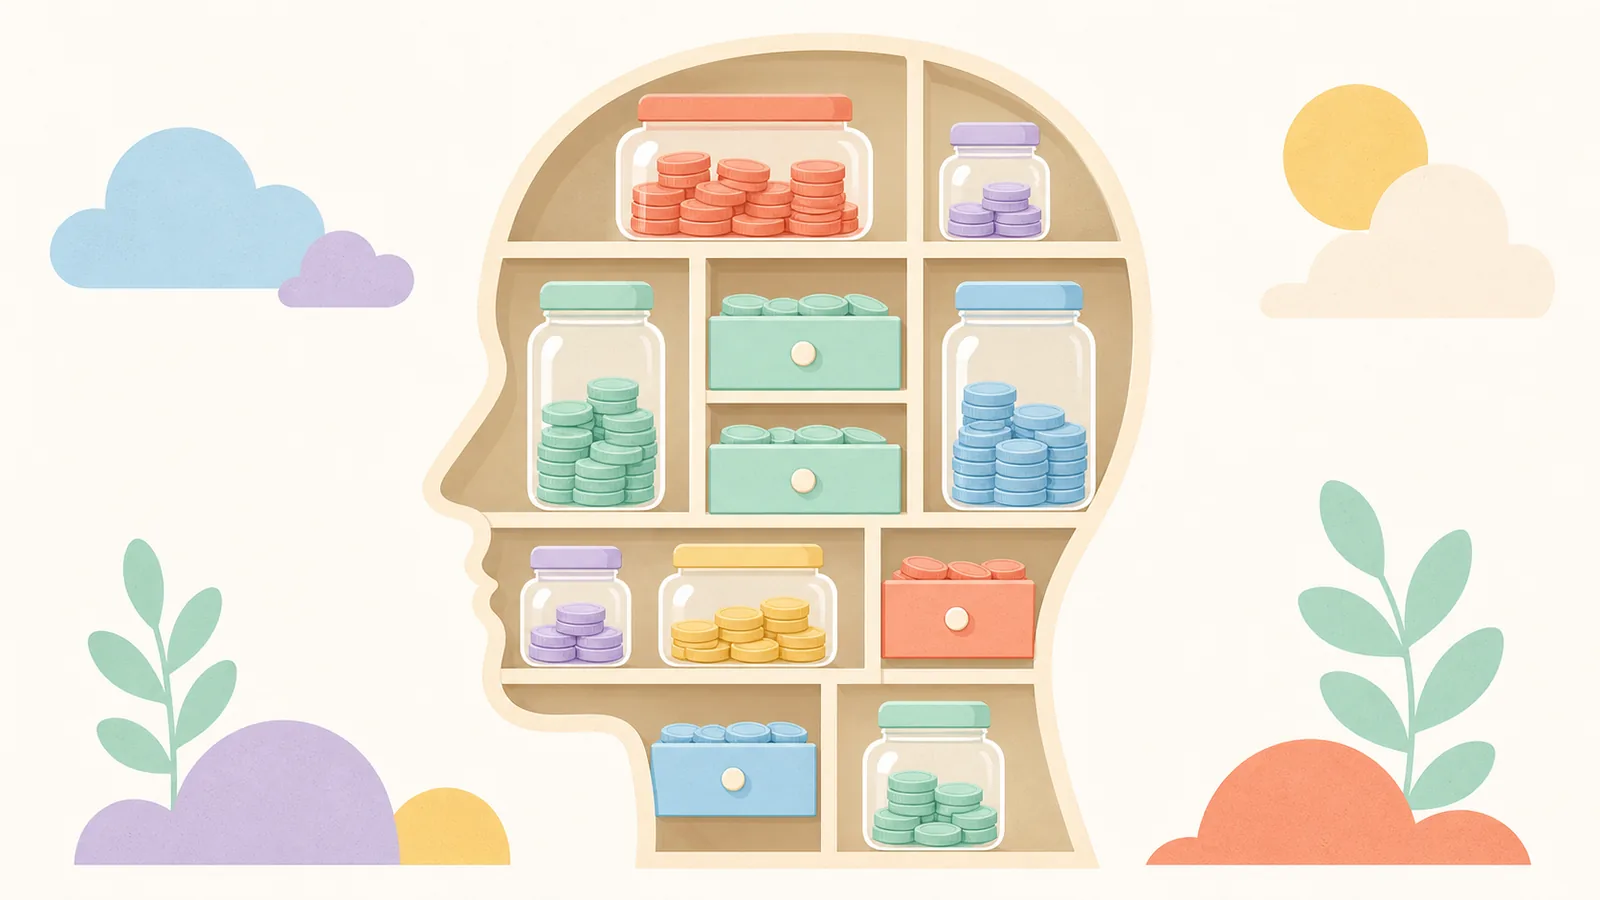
At its simplest, mental accounting is the cognitive bias where individuals treat units of money differently depending on how they obtain or intend to spend them. Economically, all money is fungible – a rupee is a rupee, regardless of whether it’s from salary, a bonus, or a lottery win. Yet, our minds create subjective ‘buckets’ for these funds, often assigning different values, risk tolerances, and spending rules to each.
For the Indian retail investor, this manifests acutely. Consider the ubiquitous ‘daughter’s marriage fund,’ ‘child’s education corpus,’ or the sacrosanct ‘retirement savings.’ Each is often treated as a distinct, insulated entity, almost as if they were separate legal trusts within one’s brain. The money allocated to the ‘daughter’s marriage’ might be locked into ultra-safe, low-yielding fixed deposits for decades, even when the time horizon warrants higher-growth assets. Conversely, a ‘speculative investment pot’ might be chased into high-risk, volatile equities without adequate diversification, simply because it’s mentally earmarked for ‘experiments.’
This isn’t mere earmarking for goals; it’s a fundamental misapplication of risk and return principles based on arbitrary mental categories.
The Indian Context: Sacred Buckets and Suboptimal Returns
The prevalence of mental accounting in India is deeply rooted in socio-cultural factors. Specific life events — a child’s education, a daughter’s wedding, securing a home, ensuring a comfortable retirement — are not just financial goals; they are emotional imperatives. This emotional weight imbues the corresponding ‘mental buckets’ with disproportionate psychological significance.
For instance, the fear of losing even a fraction of the ‘daughter’s marriage fund’ in the stock market often outweighs the rational understanding that inflation (currently at 4.45% for retail, as per recent news) will steadily erode the purchasing power of money parked in a 6-7% FD over a 15-year horizon. The nominal safety of an FD provides a potent psychological comfort, even if the real returns are negligible or negative after tax. This psychological comfort, enabled by mental accounting, directly contravenes the objective of wealth creation.
This behavioral trap leads directly to:
- Suboptimal Asset Allocation: An investor might have an aggressive equity portfolio in one ‘bucket’ and a highly conservative one in another, yet their overall risk tolerance might dictate a blended, balanced approach that is never achieved. The ‘safe’ buckets drag down the overall portfolio returns, while the ‘risky’ ones may be unnecessarily exposed.
- Inefficient Tax Management: Different mental buckets often lead to segregated tax planning, missing opportunities for integrated tax optimization across the entire portfolio. This fragmented approach often results in higher overall tax outgo.
- Emotional Investment Decisions: When one mental bucket performs poorly, it can trigger disproportionate emotional responses (e.g., panic selling) that spill over into other, unrelated buckets, disrupting a well-thought-out financial plan. This exacerbates the impact of behavioral biases like loss aversion.
Breaking the Mirage: Towards Integrated Wealth Management
Recognizing mental accounting is the first, crucial step. The antidote lies in adopting a holistic, integrated view of your personal balance sheet.
- Consolidate Your Financial Universe: Mentally, and physically, view all your assets and liabilities as a single, unified pool. Whether it’s savings in FDs, mutual funds, real estate, or gold, it all contributes to your singular net worth. There are no ‘safe’ or ‘risky’ types of money, only assets within an overall portfolio.
- Define a Single, Unified Risk Profile: Your personal risk tolerance and capacity should dictate the asset allocation for your entire investable corpus, not for individual, emotionally charged buckets. Work with a financial advisor to objectively assess your willingness and ability to take risk across all your wealth.
- Align Asset Allocation with Time Horizons, Not Labels: Instead of allocating based on the ‘purpose’ label, allocate based on the time horizon of the goal and the overall portfolio’s risk profile. A long-term goal like retirement (30+ years away) warrants a different risk profile than a short-term goal like a down payment (3 years away). An integrated approach ensures that even ‘safe’ goals benefit from growth when appropriate, while ‘risky’ goals are adequately hedged.
- Embrace Fungibility: Understand that if your ‘daughter’s marriage fund’ is currently over-allocated to FDs, and your overall portfolio needs more equity exposure, you should be able to reallocate from that ‘safe’ bucket. The capital remains available for the marriage; it’s simply working harder within a coherent strategy.
The news today highlights the Indian bond market’s stability, often seen as a bastion of safety, even as Axis Bank raises bonds at a 5.348% coupon. While bonds serve a purpose, blindly chasing nominal safety through mental accounting, especially when inflation is a constant undertow, is a disservice to your wealth. Your goal isn’t just to save; it’s to grow your purchasing power across all your financial aspirations.
The MoneyExplain Takeaway
The rational investor is a myth. For the Indian retail investor, mental accounting is a pervasive, often unconscious, barrier to optimal wealth creation. By intellectually dismantling these self-imposed financial silos and adopting an integrated, goal-oriented approach, you transition from an emotionally driven accumulator to a strategically aligned wealth manager. Stop treating your money like distinct entities; see it as a unified force, optimally deployed to serve your overarching financial future.
"This compartmentalization often results in suboptimal asset allocation, where 'safe' buckets yield low returns while 'risky' ones are under-diversified, eroding overall portfolio efficiency."
Mental accounting, a behavioral bias, leads Indian investors to irrationally segregate money into subjective mental 'buckets,' hindering optimal financial decisions.
Editorial Policy: MoneyExplain is an independent personal finance and macroeconomic publication. We do not offer investment advice, stock tips, or sell sponsored articles. Mutual Fund and equity investments are subject to market risks.