The bedrock of personal finance is often sold as a blend of discipline and diversification. Yet, for the average Indian retail investor, a far more insidious and subtle force undermines wealth creation: the twin psychological traps of familiarity bias and the recency trap. These aren’t abstract academic concepts; they are daily architects of suboptimal portfolios, silently siphoning real wealth. We, at MoneyExplain, posit that overcoming these entrenched biases is not merely advisable but fundamentally critical to achieving genuine financial independence in the Indian context.
The Familiarity Fallacy: Comfort as a Financial Killer
Familiarity bias describes our innate human preference for the known, often conflating comfort with safety, especially in financial decisions. For Indian investors, this manifests profoundly in several ways:
-
Local Real Estate Over-allocation: The emotional attachment to physical property, particularly in one’s hometown or a known locality, leads to disproportionate portfolio exposure. This isn’t just about diversification; it’s about illiquidity, concentration risk, and the opportunity cost of capital locked in an asset that may not yield market-beating, inflation-adjusted returns after factoring in maintenance, taxes, and transaction costs. A residential property purchased for personal use often becomes an investment by default, but its “safety” is an illusion if it stifles broader portfolio growth.
-
Fixed Deposits (FDs) as the Ultimate Safe Haven: Despite a decade of persistently high inflation eroding purchasing power, a significant portion of Indian household financial savings remains parked in FDs. While offering principal protection (up to DICGC limits of ₹5 lakh per bank), FDs typically yield post-tax, post-inflation returns that are often negative in real terms. The comfort of seeing a fixed amount grow numerically blinds many to the real-world reduction in their money’s buying power. This is familiarity bias at its most financially detrimental.
-
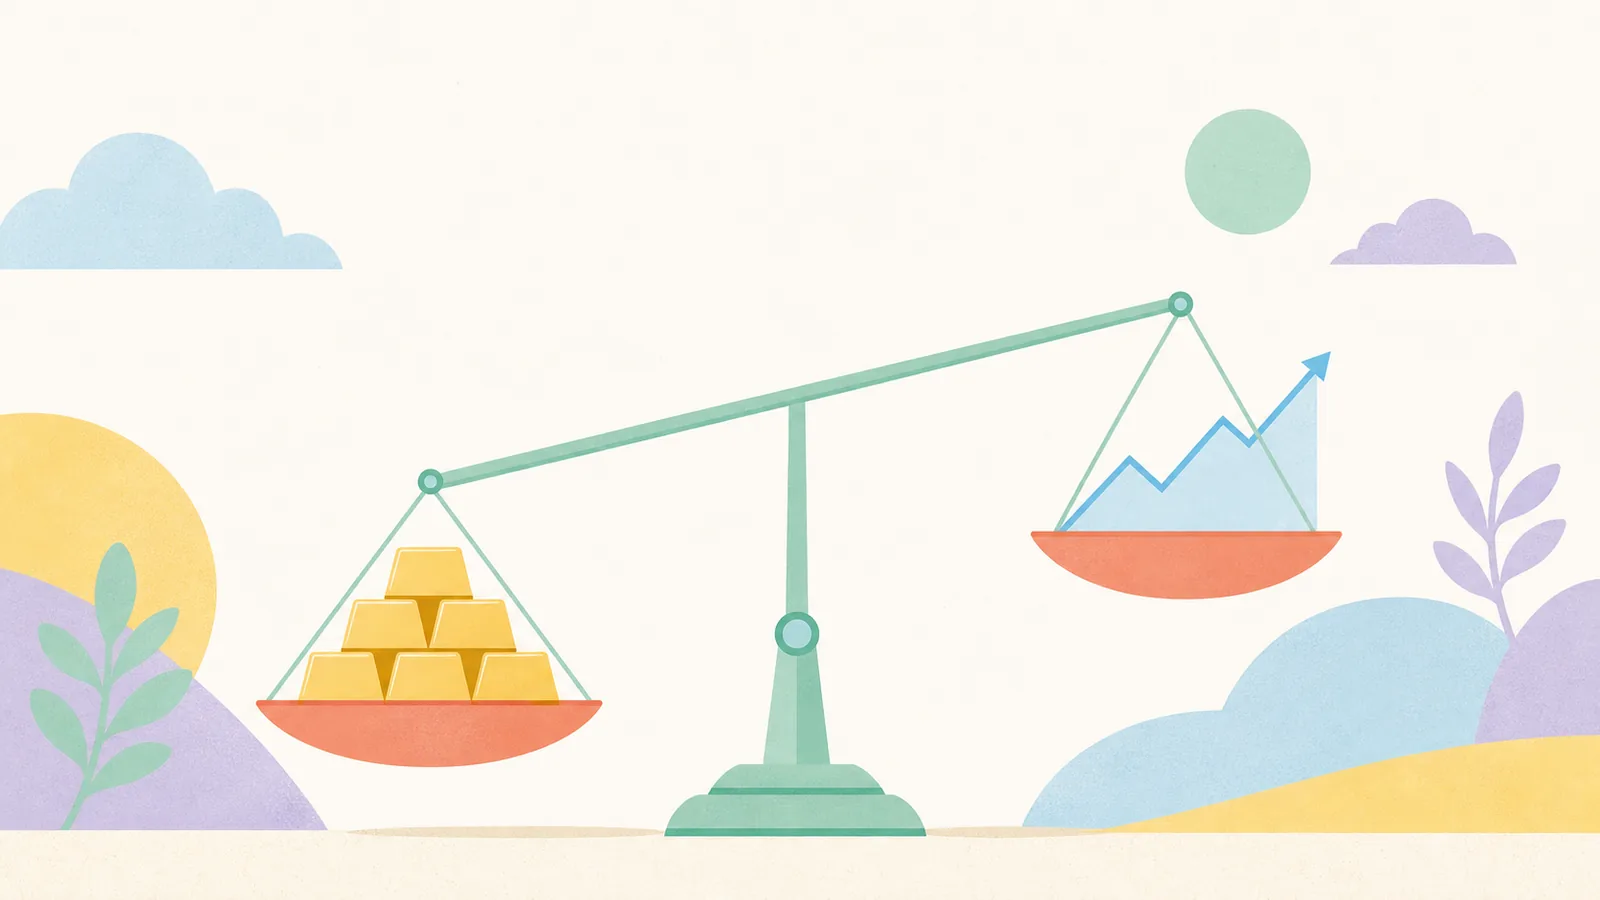
Gold (Physical) vs. Financial Instruments: The cultural affinity for physical gold often leads to storage costs, purity concerns, and suboptimal pricing on sale. While Sovereign Gold Bonds (SGBs) offer better tax efficiency, an annual interest component, and market-linked returns without physical hassles, many investors still prefer coins and jewellery. The tangible nature of physical gold provides psychological comfort, overshadowing the superior financial characteristics of SGBs or gold ETFs.
These choices, while offering psychological solace, systematically limit exposure to higher growth avenues and create concentrated portfolios vulnerable to asset-specific downturns.
The Recency Trap: Chasing the Last Quarter’s Winner
The recency trap, often working in tandem with familiarity, drives investors to extrapolate recent performance into the future. If an asset class, sector, or specific stock has performed exceptionally well over the last year, investors assume that trend will continue. The financial news cycle often exacerbates this: observing Madhusudan Kela’s portfolio stocks rallying up to 135% in CY26 can ignite a desire to chase similar high-flying assets, regardless of their intrinsic value or long-term potential. Similarly, the ongoing IPO rush, with companies raising significant capital, often sees retail participation driven by past grey market premiums or the immediate listing pops of other recent offerings, rather than deep fundamental analysis.
This bias leads to:
- Performance Chasing: Buying assets after they’ve already appreciated significantly, increasing the probability of buying high.
- Sectoral Concentration: Over-allocating to currently “hot” sectors, ignoring the cyclical nature of markets and the principle of mean reversion.
- Emotional Decision Making: Reacting to market noise rather than adhering to a pre-defined investment strategy.
While Nifty might be range-bound, the selective spotlight on individual outperformers creates a misleading narrative of ubiquitous easy gains, luring investors into the recency trap. This often results in a ‘buy high, sell low’ cycle, as investors abandon underperforming assets just before their rebound and pile into new ‘winners’ at their peak.
The Compounding Cost of Comfort and Chasing
The combined effect of familiarity and recency bias is a formidable wealth destroyer.
- Opportunity Cost: Every rupee locked into a suboptimal, familiar asset (like an FD yielding 5-6% while inflation runs at 7%) or invested impulsively into a ‘hot’ stock (that subsequently corrects) is a rupee that could have been allocated to a truly diversified portfolio yielding superior, inflation-beating returns. Over decades, this compounds into a staggering difference in net worth.
- Lack of True Diversification: Concentrated portfolios are inherently riskier. A dip in the local real estate market or a correction in the previously ‘hot’ sector can severely impact overall wealth, without the cushion of other uncorrelated assets.
- Inflation Erosion: For assets like FDs, the nominal growth offers a false sense of security. The real return, after accounting for inflation and taxes, often reduces purchasing power, turning capital preservation into capital erosion.
Breaking the Chains: An Analytical Approach
Overcoming these biases demands a deliberate, analytical, and unemotional approach to personal finance:
- Objective Portfolio Review: Conduct an annual, unsparing audit of your entire financial portfolio. Question every asset’s inclusion. Is it there because it’s genuinely aligned with your financial goals, risk tolerance, and asset allocation strategy, or because it feels “safe” or has performed well recently?
- Systematic Asset Allocation: Develop a robust, long-term asset allocation plan that considers your goals, time horizon, and true risk capacity, not just your comfort level. This plan should encompass various asset classes (equity, debt, gold, international assets, real estate) and sub-classes, ensuring true diversification.
- Dispassionate Rebalancing: Rebalance your portfolio periodically (e.g., annually) back to your target asset allocation. This forces you to sell assets that have outperformed (countering recency bias) and buy assets that have underperformed (a contrarian strategy), locking in gains and maintaining risk levels.
- Embrace the Unfamiliar (Strategically): Research and understand asset classes or investment vehicles that might seem less familiar but offer better risk-adjusted returns (e.g., REITs, debt funds, international equity funds, P2P lending platforms, venture debt for accredited investors). Knowledge dispels familiarity bias.
- Professional Guidance: An independent financial advisor can provide an objective perspective, acting as a behavioral circuit breaker against impulsive decisions driven by bias. Their role is to keep you anchored to your plan, not to the latest market fad or your comfort zone.
The MoneyExplain Takeaway
The illusion of safety born from familiarity and the lure of quick gains from recency are silent, pervasive threats to the Indian investor. They compel us to make financially suboptimal choices, prioritizing psychological comfort over real wealth accumulation. True financial prudence lies in recognizing these deep-seated behavioral traps and consciously adopting a disciplined, data-driven, and diversified approach. Your net worth isn’t just a function of market returns; it’s a testament to your ability to master your own psychology. Challenge your comfort, question the hype, and build a portfolio designed for the future, not just anchored to the past.
"Recency bias causes investors to chase assets or sectors that have recently performed well, neglecting underlying fundamentals and long-term strategy."
Familiarity bias leads investors to over-allocate to 'known' assets (e.g., local real estate, FDs), creating an illusion of safety.
Editorial Policy: MoneyExplain is an independent personal finance and macroeconomic publication. We do not offer investment advice, stock tips, or sell sponsored articles. Mutual Fund and equity investments are subject to market risks.