The Indian financial landscape, perpetually in flux, often presents retail investors with instruments that promise multifaceted benefits. Among these, the Unit-Linked Insurance Plan (ULIP) stands out—a product pitched as the perfect confluence of investment growth and life insurance coverage, bundled into a single, tax-efficient wrapper. Yet, for the discerning investor, a rigorous examination reveals ULIPs are less a synergistic powerhouse and more a compromise, an expensive illusion that often underperforms against its unbundled counterparts.
The Structural Flaw: A Confluence of Conflicts
At its core, a ULIP attempts to marry two fundamentally distinct objectives: risk mitigation (insurance) and wealth creation (investment). This hybridity, while seemingly convenient, is its Achilles’ heel. Insurance thrives on risk pooling and defined payouts, whereas investment prospers through compounding growth and minimized friction costs. In a ULIP, these objectives inevitably clash, with the financial engine often sabotaged by a cascade of charges.
Retail investors are frequently lured by the promise of Section 80C deductions on premiums and Section 10(10D) tax-free maturity proceeds. However, this tax efficiency often distracts from the devastating impact of the internal cost structure. ULIPs are notorious for their opacity and myriad deductions, including:
- Premium Allocation Charges: A significant chunk of your initial premium is siphoned off even before it’s invested. This front-loading severely curtails the capital available for market exposure, impacting long-term compounding.
- Policy Administration Charges: Regular deductions from your fund value to cover administrative costs, irrespective of fund performance.
- Fund Management Charges (FMC): Levied annually as a percentage of your fund’s assets. While present in mutual funds, ULIP FMCs can often be higher, or at par with regular mutual funds, without the same level of transparency or flexibility.
- Mortality Charges: The cost of your life cover, deducted from your fund value. As you age, these charges naturally escalate, further eroding your investment corpus.
- Discontinuance Charges: Penalties for surrendering or making your policy paid-up within the initial lock-in period (typically 5 years). This traps capital, limiting liquidity and investment flexibility.
Even after the IRDAI’s rationalization of ULIP charges post-2010, the aggregate drag of these fees remains substantial. A typical ULIP might see as much as 10-20% of the first year’s premium vanish in charges, followed by consistent deductions over its tenure. This fundamental erosion of capital makes it an uphill battle to generate competitive market-linked returns.
The Psychological Anchor: Convenience & Misplaced Trust
The persistent appeal of ULIPs isn’t purely rational; it’s deeply rooted in behavioral finance. The allure of a single, convenient product for both insurance and investment taps into our inherent bias for simplicity. This “convenience premium” blinds investors to the sub-optimal outcomes.
Furthermore, distributor incentives play a crucial, often detrimental, role. ULIPs historically offer higher commissions to agents compared to pure term insurance or direct mutual funds. This creates an agency problem, where the advisor’s financial incentive may diverge from the client’s optimal financial well-being. Indian investors, often placing implicit trust in their financial advisors, may overlook the fine print, drawn in by glossy brochures highlighting projected returns that rarely materialize after all charges. The perceived “tax-free” maturity under Section 10(10D) becomes a powerful anchoring bias, overshadowing the actual wealth destruction.
Beyond the Gloss: A Dissection of Real-World Performance
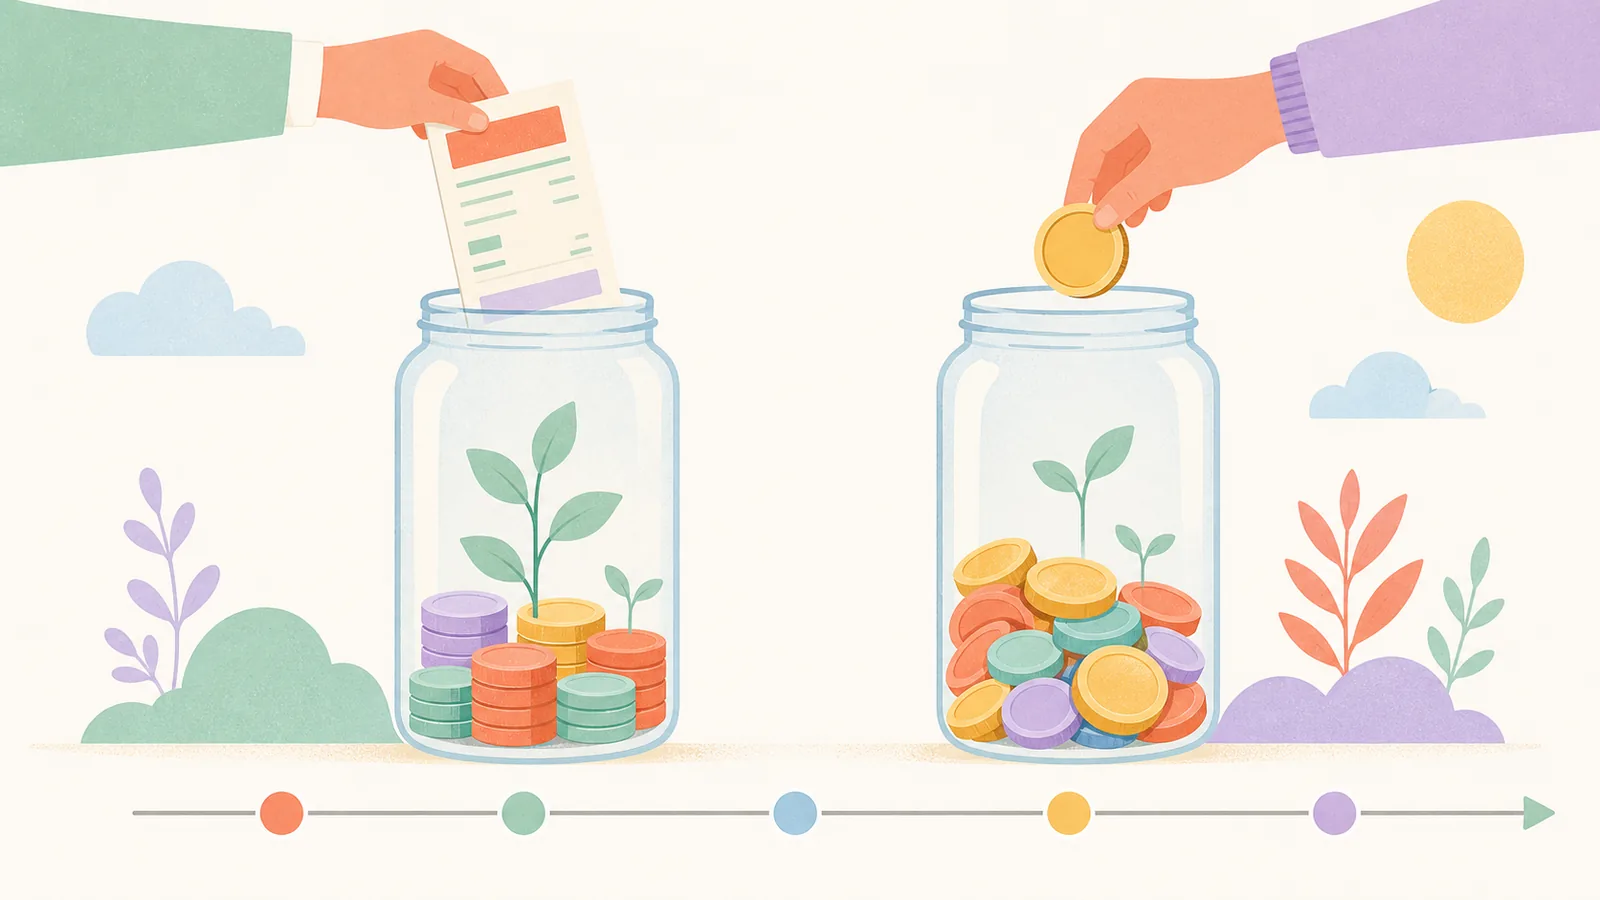
Consider a practical scenario. An investor opts for a ULIP with an annual premium. The first year, a significant portion is lost to premium allocation charges. Subsequent years see ongoing deductions for administration, fund management, and rising mortality costs. Comparing this to a strategy of purchasing a pure, low-cost term insurance plan and investing the remaining premium in diversified direct mutual funds reveals a stark difference.
Pure term insurance provides substantial life cover at a fraction of the cost, ensuring family protection is robust and efficient. The freed-up capital, channeled into direct mutual funds, benefits from lower expense ratios, greater transparency, and the flexibility to switch funds or rebalance portfolios without punitive charges. Over a 15-20 year investment horizon, the compounding effect on a larger, undiluted principal in direct mutual funds almost invariably outpaces the net returns of a ULIP. While ULIPs offer fund switching options, these are often limited to internal funds managed by the insurer, lacking the breadth and competitive pricing of the broader mutual fund universe.
The lock-in period of five years further exacerbates the problem. During this time, the investor is effectively trapped, unable to redeploy capital to potentially better-performing or more appropriate assets without incurring substantial penalties. This inflexibility represents a significant opportunity cost in India’s dynamic economic environment.
The MoneyExplain Takeaway
The premise of ULIPs—integrated financial solutions—is fundamentally flawed. By attempting to serve two masters, they compromise both objectives. For the Indian retail investor seeking genuine wealth creation and robust financial protection, the optimal strategy remains a clear segmentation:
- Pure Term Insurance for Protection: Secure adequate life cover through a plain-vanilla term plan. These are cost-effective, transparent, and ensure your dependents are financially safeguarded without complicating your investment goals.
- Direct Mutual Funds for Investment: Channel your investment capital into a diversified portfolio of low-cost direct mutual funds. This approach offers transparency, flexibility, and significantly higher net returns over the long term, free from the multi-layered charge structures of ULIPs.
Resist the psychological appeal of a “two-in-one” solution that frequently delivers less than one. Disentangle your financial objectives, embrace transparency, and build wealth with instruments designed for specific, optimized outcomes. The illusion of integrated wealth in ULIPs often proves to be an unnecessarily expensive lesson.
Full Net Real Return
Compounded Fee & Inflation Friction
Editorial Policy: MoneyExplain is an independent personal finance and macroeconomic publication. We do not offer investment advice, stock tips, or sell sponsored articles. Mutual Fund and equity investments are subject to market risks.