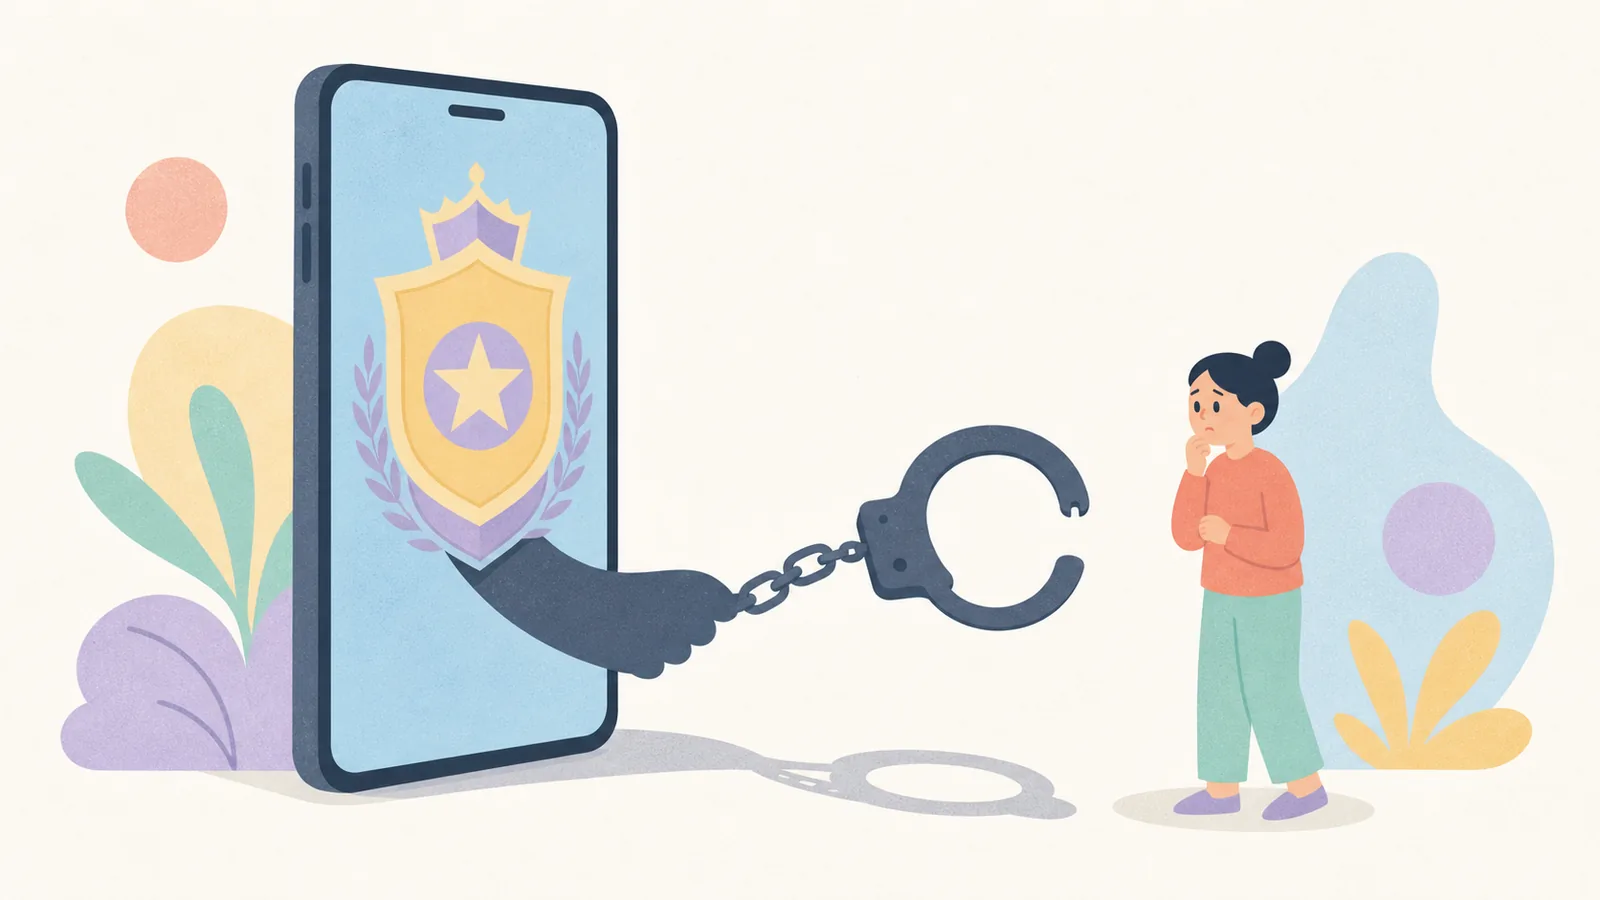
The landscape of financial fraud in India has evolved beyond the rudimentary phishing email or the obvious Ponzi scheme promising improbable returns. Today’s sophisticated scam targets not merely greed, but an even more potent human vulnerability: fear of authority and legal repercussion. We are dissecting the “Digital Arrest” scam, a meticulously engineered psychological trap that has claimed countless victims, often financially literate individuals who would scoff at simpler cons.
This isn’t about ignoring unsolicited emails. This is about being ensnared in a web so intricate, so psychologically taxing, that rational decision-making is systematically dismantled. The scam exploits India’s hierarchical respect for government institutions, specifically the RBI, CBI, Narcotics Bureau, and local police.
The Architecture of Coercion: A Psychological Blueprint
The Digital Arrest scam doesn’t just happen; it’s a multi-stage process of psychological conditioning and coercive control.
Stage 1: The Authority Hook – Initiating Fear and Compliance
The scam typically begins with an unsolicited call, often via VoIP, displaying a spoofed number that appears legitimate (e.g., from the RBI, a bank, or even a police station). The caller, often speaking impeccable Hindi or English, presents a grave, urgent scenario:
- “Your Aadhaar/PAN card has been misused for drug trafficking/money laundering in Mumbai/Delhi.”
- “A large sum of money has been found in an account linked to your name, involved in illegal activities.”
- “Your bank account is about to be frozen by the RBI/CBI due to suspicious transactions.”
This initial contact immediately triggers fear and authority bias. Victims, conditioned to respect official institutions, are primed for compliance. The urgency prevents critical thought, as the alleged crime is severe, and the consequences (arrest, asset seizure) are terrifying. Research indicates that individuals under high cognitive load or emotional distress are significantly more susceptible to manipulation.
Stage 2: The Credibility Cascade – Building an Inescapable Narrative
The initial call transitions seamlessly into a more ‘official’ communication. The victim is often “transferred” to a “CBI officer,” “RBI official,” or “police inspector,” sometimes even via a video call on WhatsApp where the fraudster is in uniform or a formal setting. This multi-layered impersonation reinforces legitimacy. They present fake FIRs, official-looking documents via WhatsApp, or even ‘court orders’.
The “officials” use specific Indian legal jargon, reference real laws (PMLA, NDPS Act), and cite relevant sections, lending an air of authenticity. They might even ‘verify’ the victim’s identity using publicly available data, making the scenario intensely personal and seemingly undeniable. This leverages the consistency principle; having initially accepted the authority, victims find it harder to disbelieve subsequent ‘evidence’.
Stage 3: The “Safety Account” Ruse – The Ultimate Financial Trap
This is the critical juncture where funds are extracted. The “officials” demand that the victim transfer all their funds to a “CBI safety account,” “RBI escrow account,” or a “police safe wallet” for “verification” and “protection” from being implicated in the supposed crime.
- The lie: They claim this is necessary to prove the money is “clean” and not linked to illegal activities. They assure the funds will be returned once the “investigation” is complete.
- The manipulation: They often instruct the victim to open a new bank account or use a specific online payment gateway, sometimes even guiding them to install remote access apps to ‘assist’ with the transfer. They explicitly forbid discussing this with anyone, including bank staff, under threat of further legal action or obstruction of justice. This creates social isolation, a known tactic in cults and coercive control, preventing external reality checks.
Crucially, no legitimate law enforcement or regulatory agency in India ever demands money transfers to a ‘safety’ or ‘escrow’ account for investigation. This is the definitive red flag. Indian banks have robust KYC and AML processes. Funds are frozen, not transferred to nebulous ‘safety accounts’. Yet, under immense psychological pressure, with threats of imminent arrest, imprisonment, or public humiliation, victims comply. They are often kept on the phone for hours, unable to disconnect and process the situation rationally.
The MoneyExplain Takeaway
The Digital Arrest scam is a stark reminder that investment security extends far beyond market volatility or fund performance. It deeply penetrates the realm of behavioral finance, demonstrating how cognitive biases like authority bias, fear, and urgency can override even the most astute financial judgment. While the recent news of the Rupee nudging up or Tata Motors’ Q1 results might occupy market discussions, the insidious creep of such sophisticated frauds poses a more direct and immediate threat to an individual’s capital.
Protecting your finances from this sophisticated threat requires an institutional-grade defense: extreme skepticism and independent verification. No matter how convincing the narrative, how authoritative the voice, or how legitimate the documents appear, the moment money transfer to an unknown “safety account” is demanded, it is a fraud. Disconnect, independently verify through official government or bank websites, and immediately report such attempts. Your critical thinking is your strongest shield against these unseen chains of cognitive coercion.
The Trigger Hook
Digital arrest exploits fear and authority bias, not just simple greed, to manipulate victims.
The Structural Drag
Scammers use multi-layered impersonation (RBI, CBI, Police) to create a highly coercive, inescapable environment.
The Real Outcome
Never trust caller ID; verify *any* official demand by independently contacting the concerned agency via its official website/numbers, not those provided by the caller.
Editorial Policy: MoneyExplain is an independent personal finance and macroeconomic publication. We do not offer investment advice, stock tips, or sell sponsored articles. Mutual Fund and equity investments are subject to market risks.